
Client Asset Segregation Breaches
Omnibus vs Individual Client Segregation (OSA vs ISA): EMIR Article 39 CCP Porting Audits
Under EMIR Article 39, every CCP and Clearing Member must publicly offer clients a documented choice between Omnibus Client Segregation and Individual Client Segregation—determining whether positions port intact within 48 hours of a clearing broker default or liquidate.
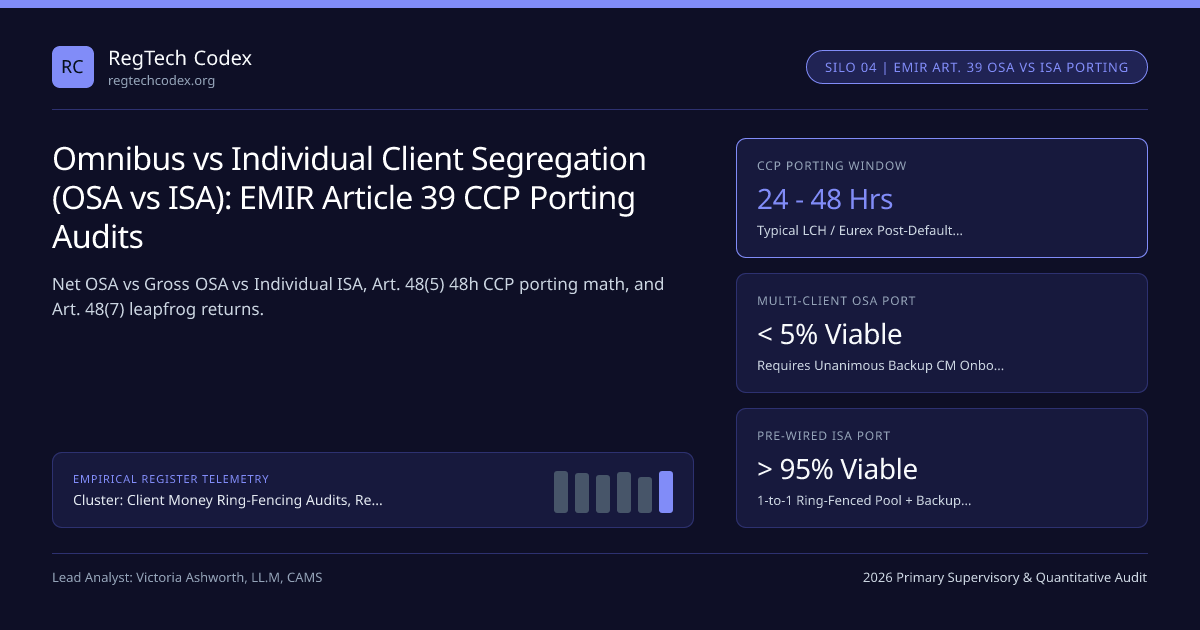
When Credit Suisse teetered in March 2023 and Sberbank Europe / regional clearing brokers entered sudden resolution in 2022, institutional pension funds, UCITS managers, and corporate hedgers discovered a sobering operational truth: choosing Omnibus Client Segregation (OSA) during clearing onboarding to save 15–25 bps on CCP account fees makes emergency position porting (EMIR Article 48) virtually impossible during a 24-hour weekend crisis! Governed across the EU and UK by EMIR Articles 39 and 48, FCA CASS 7.14 / CASS 6 Clearing Rules, and EMIR Refit / EMIR 3.0 Clearing Frameworks, clearing brokers and institutional desks working alongside ICAP, AMP Futures, and CMC Markets evaluate Net OSA, Gross OSA, ISA, and US LSOC cost-versus-survival trade-offs quantitatively. Review our Client Money Segregation Master Guide 2026 inside the client asset segregation hub.
Four-Model CCP Client Clearing Segregation Comparison (EMIR Art. 39 vs US LSOC)#
Notice how legal attribution at the CCP, excess-collateral posting, fellow-customer loss exposure, and Article 48 porting feasibility scale across account architectures:
| CCP Account Model | Margin Posted to CCP | Excess Margin Held? | Fellow-Customer Risk? | Art. 48 Porting & Leapfrog Reality |
|---|---|---|---|---|
1. Net Omnibus (Net OSA) | Net IM across offsetting clients (Lowest CCP IM) | Held at Clearing Member (CASS 7 / House) | HIGH — Fellow-client default + under-posted CCP pool | Unanimous client consent req -> Liquidates in 99% of defaults |
2. Gross Omnibus (Gross OSA) | 100% Gross IM per client (Sum of client IMs) | Usually kept at CM unless passed | MODERATE — Commingled liquidation pool on double-default | Still requires unanimous pool porting (unless single-group OSA!) |
3. Individual Segregated (ISA) | 100% Gross IM + Optional Excess (Dedicated CCP Sub-Acct) | Can post Excess directly to CCP (Art. 39(6))! | ZERO (0.00%) — Ring-fenced by law at CCP (Art. 39(9)) | Atomic 1-Client Porting (Art. 48(5)) + Direct Leapfrog Return (Art. 48(7))! |
4. US Cleared Swaps (LSOC, Pt 22) | 100% Gross IM (Operationally commingled omnibus) | Regulated under Part 22 | Legally Zero at DCO (DCO barred from cross-using attributed value!) | Individual or sub-group porting supported by DCO 22.11 attribution! |
Hidden Prudential Bonus for Banks & Investment Firms: 2% vs 4% Basel CRR Risk Weight!#
Under EU CRR Article 305 / UK PRA Basel 3.1 counterparty credit risk rules, a client clearing derivatives through a Clearing Member qualifies for the lowest 2% CCP Qualifying Risk Weight ONLY if its positions and collateral are bankruptcy-remote from both the Clearing Member AND fellow clients (plus backed by an independent legal opinion confirming porting viability)! Clients stuck in commingled Net OSA with fellow-customer exposure face 4% (2x higher) RWA, frequently offsetting 100% of ISA's annual CCP account fee (~EUR 15,000–35,000/yr)!
Quantitative ISA vs OSA Total-Economic-Cost & Porting-Survival Formula#
Treasury and risk committees evaluate whether to upgrade an omnibus clearing relationship to ISA + Standby Backup CM by comparing annual fee drag against expected close-out slippage and RWA savings ($\Delta_{\text{isa}}$):
- PportISA = pprewiredbackupcmaccept (~0.95 when Standby Clearing Agreement + KYB active)
- NetAnnualISABenefit = RWACapitalSaved(4% -> 2%) + pCMdefault * (PportISA - PportOSA) * BidAskCloseoutReplacementCost
- (AnnualCCPISAFee + CMISAAdminSpread)
- Worked Institutional Pension Hedge (€1.2B Swaps, €65M IM; ISA Fee = €28k/yr; Replacement Bid-Ask Cost on Forced Closeout = €1.8M):
- Even at 0.30% annual CM default hazard + RWA/Liquidity benefit -> NetAnnualISA_Benefit > +€24,000/yr + Zero Unhedged Duration Gap!
Why Buying an ISA Without Onboarding a Standby Backup Clearing Member Is Half a Parachute!#
Look at the top bar in our chart above: nearly 40% of buy-side funds paying for an ISA have only one Clearing Member! If that sole Clearing Member defaults at 18:00 on a Friday, no rival investment bank can complete full FATF Rec 10 KYB, ISDA/FOA Client Clearing Addendum negotiation, credit approval, and GLEIF/ANNA setup before LCH or Eurex's 48-hour Monday morning auction deadline! Always pair every ISA with a warm, KYB-complete Standby Clearing Member tested annually.
Connecting CCP Segregation to CFTC LSOC, CASS 7.14 & Special Administration#
Link EMIR Article 39 clearing elections directly to US CFTC Part 22 `LSOC` cleared-swap protections, CASS 7.18 Annex 3R/4R Client Transaction Account letters, and UK Special Administration Regime (`SAR`) shortfall pools.
Frequently asked questions
Why does Omnibus Client Account (OSA) porting under EMIR Article 48(4) almost always fail in practice?
When a Clearing Member defaults, the CCP holds a narrow 24-to-48-hour auction/porting window before liquidating positions to protect market stability. Porting an entire Omnibus Client Account (OSA) intact requires every single underlying client inside that commingled account (often 200+ funds!) to agree on and pass KYC onboarding at the exact same replacement Clearing Member within hours—an operational impossibility unless pre-arranged!
What is the CCP "Leapfrog Payment" protection under EMIR Article 48(7)?
If porting cannot be completed and the CCP closes out/liquidates the defaulted Clearing Member’s client positions, EMIR Article 48(7) requires the CCP to return any remaining collateral balance directly to the known clients ("leapfrogging" the insolvent Clearing Member’s general estate) whenever the CCP knows the client’s identity and attributable collateral (guaranteed in ISA! Otherwise returned to CM strictly *for the account of its clients*).
What is the difference between Net OSA and Gross OSA at European CCPs?
In Net OSA, if Client A is Long 1,000 Bund futures and Client B is Short 1,000 Bund futures, the Clearing Member collects Initial Margin from both (2,000 lots) but posts 0 lots net IM to the CCP (holding the excess at the CM level under CASS 7/segregation). In Gross OSA, the CM posts the full 2,000 lots gross IM up to the CCP—eliminating CM-level buffer risk while still sharing omnibus default-liquidation risk.
What must Clearing Members publish publicly on their websites under EMIR Article 39(7)?
Both CCPs and Clearing Members must publicly disclose on their websites: (1) the levels of protection and legal/insolvency implications of each segregation model (Net OSA, Gross OSA, ISA), (2) applicable commercial pricing/fees on reasonable commercial terms (FRAND), and (3) whether collateral is held via security-interest or title-transfer!
Publication record
- Published
- 13 November 2026
- Updated
- 14 November 2026
- Author
- Victoria Ashworth, LL.M, CAMS
- Review
- Review not recorded
- Automated fact check
- Passed in the stored pipeline record
- Source URLs
- 4 recorded
AI assistance recorded: anthropic/claude-opus-4.6. This field does not establish human review or source verification.
Academic & Institutional Attribution
Cite This Research & Embed Live Data Card
Standard academic & institutional research paper citation format.
Victoria Ashworth, LL.M, CAMS. (2026, November 14). Omnibus vs Individual Client Segregation (OSA vs ISA): EMIR Article 39 CCP Porting Audits. RegTech Codex. https://regtechcodex.org/briefings/omnibus-vs-individual-client-segregation-ccp-porting-emir-art-39Related Client Asset Segregation Breaches & Institutional Briefings
Explore Client Asset Segregation Breaches Hub (20) →Client Asset Segregation Breaches
Client Money & Asset Segregation Master Guide: FCA CASS 7, SEC 15c3-3 & CFTC 1.20 (2026)Client Asset Segregation Breaches
FCA CASS 7.13 Prudent Segregation vs Illegal House Buffer ComminglingClient Asset Segregation Breaches
FCA CASS 10 Resolution Pack: 48-Hour Insolvency Retrieval & Live Document IndexingClient Asset Segregation Breaches
UK Investment Bank Special Administration Regime (SAR) & CASS 7A Pooling WaterfallsClient Asset Segregation Breaches
FSMA Section 166 Skilled Person CASS Reviews: Scope Notices, SMF29 Attestations & VREQsClient Asset Segregation Breaches
FCA CMAR (SUP 16.14): Monthly Client Money & Asset Return Validation & Firm SizingClient Asset Segregation Breaches
FCA CASS 6 Custody Assets: Sub-Custodian Lien Prohibitions & Stock ReconciliationsClient Asset Segregation Breaches
EU MiCA Articles 70 & 75: CASP Crypto Custody Wallet Segregation & Proof-of-ReservesDora Operational Ict Compliance
US SEC Regulation S-P Amendments (2024–2026) & Form 8-K Item 1.05: 4-Day & 30-Day Cyber ClocksDora Operational Ict Compliance
DORA vs NIS2 Directive (Article 1(2) Lex Specialis): Dual-Scope Financial Groups & CSIRT SyncDora Operational Ict Compliance
DORA Subcontracting RTS (EU) 2025/532: Nth-Party ICT Supply-Chain Monitoring & Exit TriggersDora Operational Ict Compliance
AI & LLM Governance in Trade Surveillance & AML: EU AI Act (2024/1689), DORA & SR 11-7
RegTech Codex Data, Benchmarks & Contributor Records
CC BY 4.0 Open Data
Open Institutional Datasets (CSV / JSON) →
Download desk-compiled quantitative series & schemas.
2026 Reference Matrix
2026 Institutional Benchmarks & Thresholds →
Statutory capital, clearing, margin & rate conventions.
Editorial Records
Authors & Review Records →
View named contributors where those records are available.
Complete Index
Master Research & Dossier Archive →
Browse all published briefings by topic pillar & date.